
TL;DR: In a November 5 speech, the European Central Bank said 36 payment service providers have been selected for a planned digital euro pilot in the second half of 2027. The pilot is intended to last 12 months, while legislation and any eventual decision to issue a digital euro remain separate steps.
Europe’s digital euro project has moved into a more practical phase of planning, but it is not launching as a public currency today. The European Central Bank has outlined how its coming pilot would involve banks and other payment providers testing the proposed system.
In the ECB’s November 5 speech on the future of money, the bank said it had selected 36 payment service providers after receiving more than 50 applications. It expects the pilot to begin in the second half of 2027 and run for a year.
What is being tested
The ECB describes the pilot as an opportunity to test not just technology but the payments ecosystem around it. Merchants, service providers, central banks and users need to work together if a new form of public digital money is to operate smoothly. A technically successful ledger is not sufficient if consumers cannot pay easily or businesses cannot reconcile receipts.
That means questions around wallets, acceptance, integration and everyday usability matter alongside resilience and security. A digital euro would also differ fundamentally from a private stablecoin: it is a project for central bank money, whereas stablecoins are claims under arrangements established by private issuers and their reserve structures.
The selection of participants does not mean the digital euro has been approved for general issuance. The ECB says political negotiations are ongoing, and a potential first issuance is targeted for 2029 only if the legislative process is completed on the expected timetable.
Why crypto markets should pay attention
Stablecoin issuers and crypto payment services are developing around fast settlement and programmable infrastructure. A retail central bank digital currency could create a different kind of digital payment option, with separate rules on privacy, intermediaries and public trust. Those choices will shape whether users view the systems as competitors, complements or tools for different purposes.
Payments systems must also solve less glamorous problems: disputed transactions, offline access, fraud controls, accessibility and interoperability with existing banks. These are precisely the issues that determine whether a project graduates from a demonstration to a useful consumer service.
The move sits alongside private-sector efforts to modernise settlement. NewsBTC has previously covered the effort to bring delivery-versus-payment tools onto Solana, though that institutional use case is distinct from the ECB’s proposed retail digital currency.
The dates that matter
For now, 2027 is the pilot window, not a promised public launch. The ECB’s stated potential issuance year is 2029, conditional on legislation and subsequent decisions. Reports that collapse these stages risk giving readers the impression that the project is more advanced than the central bank itself claims.
The next revealing milestones will be the pilot design, merchant participation, privacy arrangements and how lessons from testing affect the final proposal. Europe is preparing to test digital public money at a meaningful scale, but it still has to show how that money would improve real payment experiences.
This article was written by the News Desk and edited by Samuel Rae.
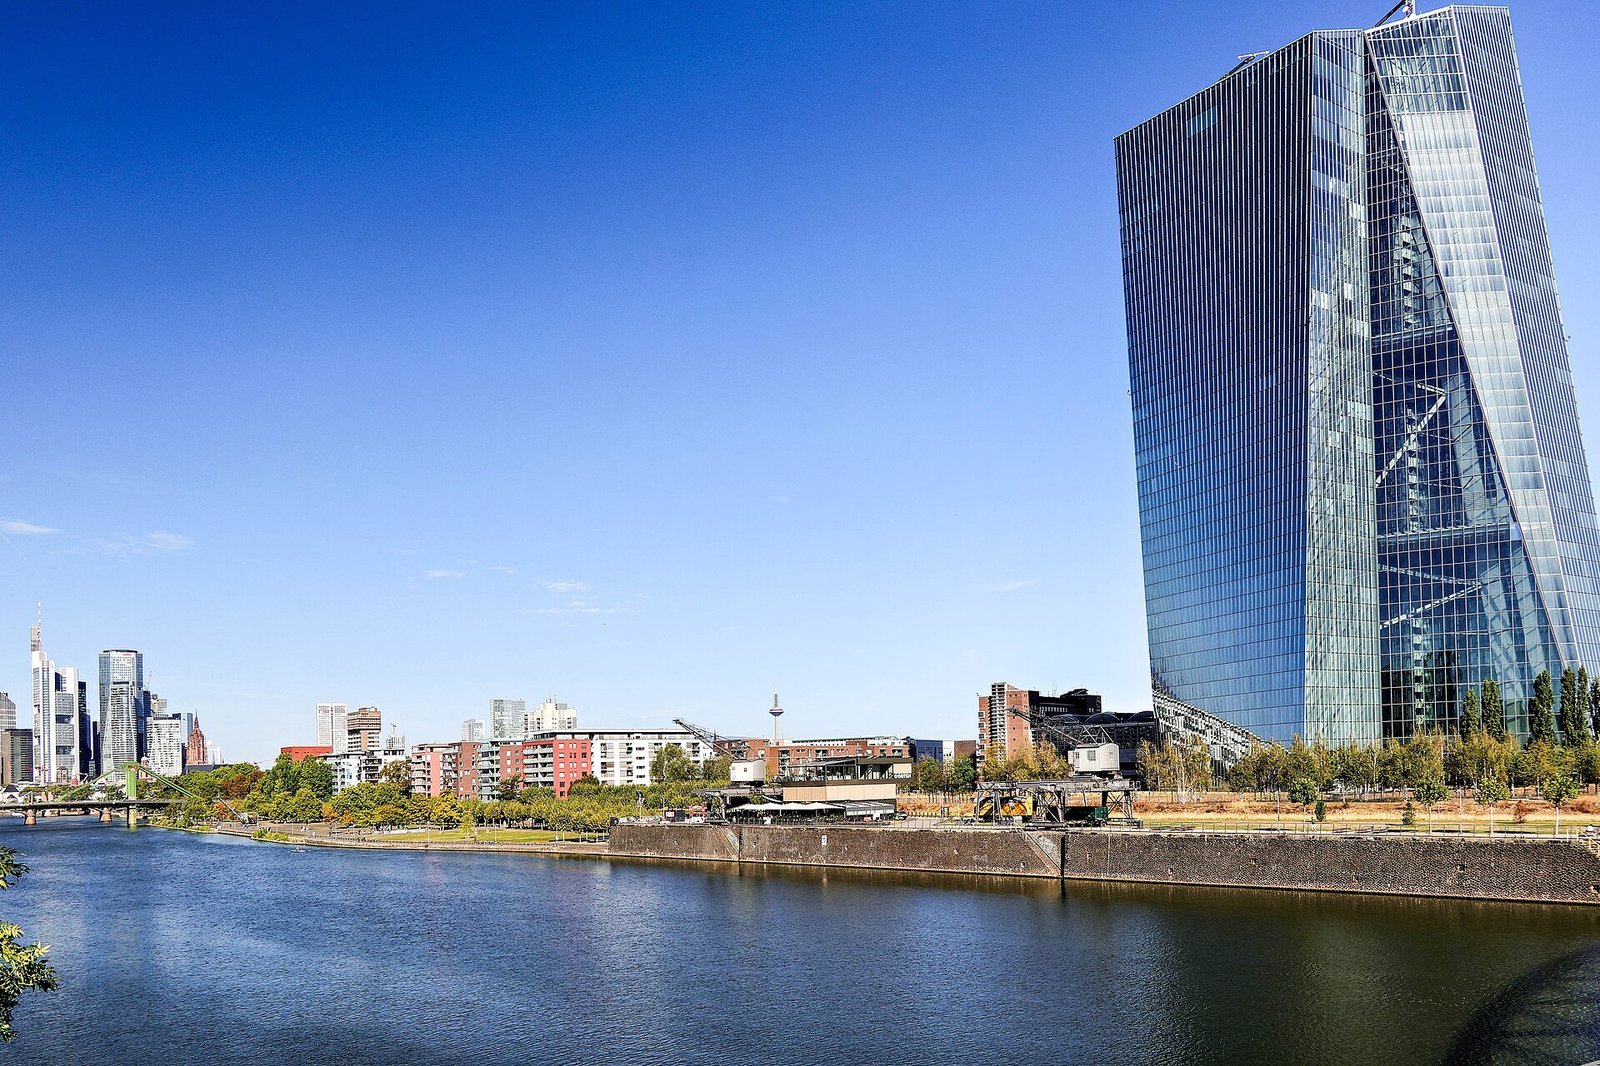
Featured image: Seat of the European Central Bank in Frankfurt am Main, Germany. Photo: Dr. Thomas Liptak via Wikimedia Commons, licensed under CC BY-SA 4.0.
).jpg)